France is facing a severe fiscal squeeze as borrowing costs climb to their highest levels in nearly 25 years amid the country's worst social unrest in decades. Yields on French government bonds have risen sharply as investors demand higher risk premiums for holding public debt, reflecting deep-seated market anxiety over the nation's financial trajectory.
The European regime's national debt has escalated to roughly 120 percent of gross domestic product, marking its highest level since the immediate aftermath of World War II. Ten-year bond yields have jumped more than 130 basis points since June to surpass 4.9 percent. This surge is driven by a widening gap between government spending and revenues, compounded by a paralyzed and bitterly divided political landscape.
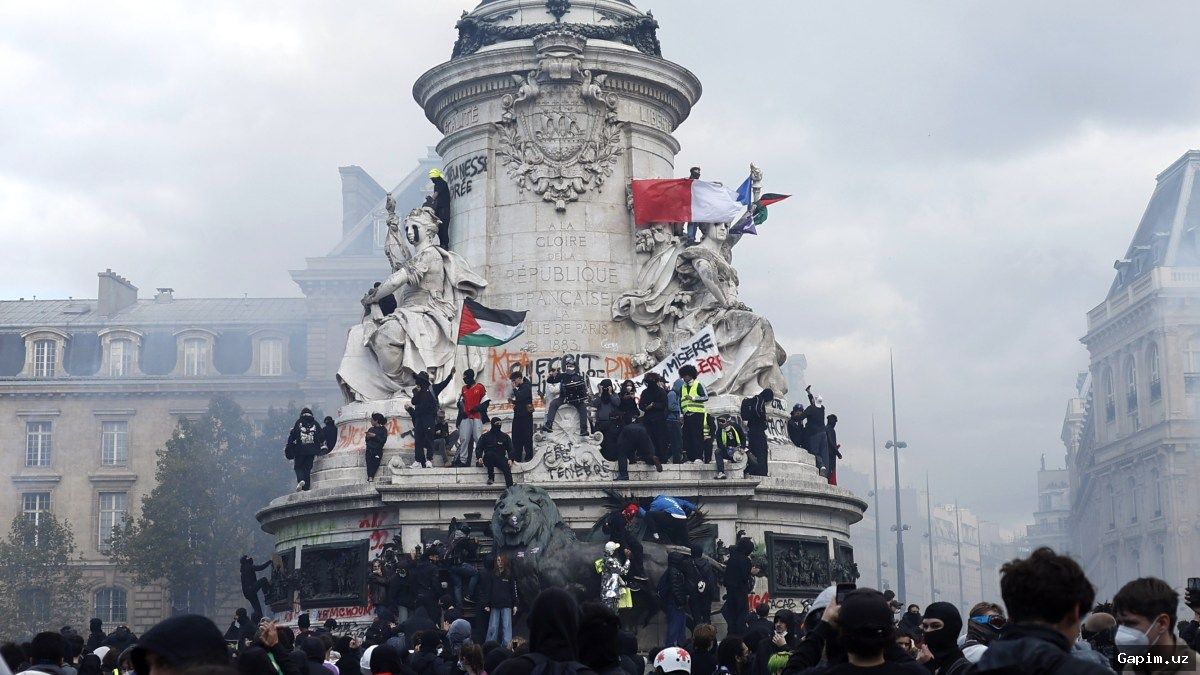
Prime Minister Sébastien Lecornu is struggling to steer a contentious budget through a fragmented National Assembly, facing staunch opposition from both far-right and far-left factions over proposed savings of 54 billion euros. Meanwhile, hundreds of thousands of protesters have taken to the streets to denounce proposed austerity measures, with some demonstrations devolving into riots and looting.
Analysts note that France's deficit is projected to hit 5.4 percent of GDP in 2026—significantly above the European Union average—while anaemic economic growth further limits the government's fiscal headroom. Economists warn that prolonged political gridlock and failure to implement structural reforms risk isolating France economically and steering the nation toward a full-blown debt crisis.
Source: www.aljazeera.com