The government of Prime Minister Narendra Modi is poised to levy new charges for using India's popular, homegrown instant digital payment system for select merchant transactions, raising concerns for businesses. India's quasi-governmental National Payments Corporation of India (NPCI) has announced that a 0.4 percent fee will apply from October 15 to all UPI (Unified Payments Interface) transactions above 2,000 rupees ($21) made to businesses. The levy, called the Merchant Discount Rate (MDR), shifts the cost of maintaining the digital payment infrastructure to businesses. So far, the costs of operating UPI have been borne by banks and fintech companies, which have also benefited commercially from the system, while government incentives have supported its zero-MDR model.
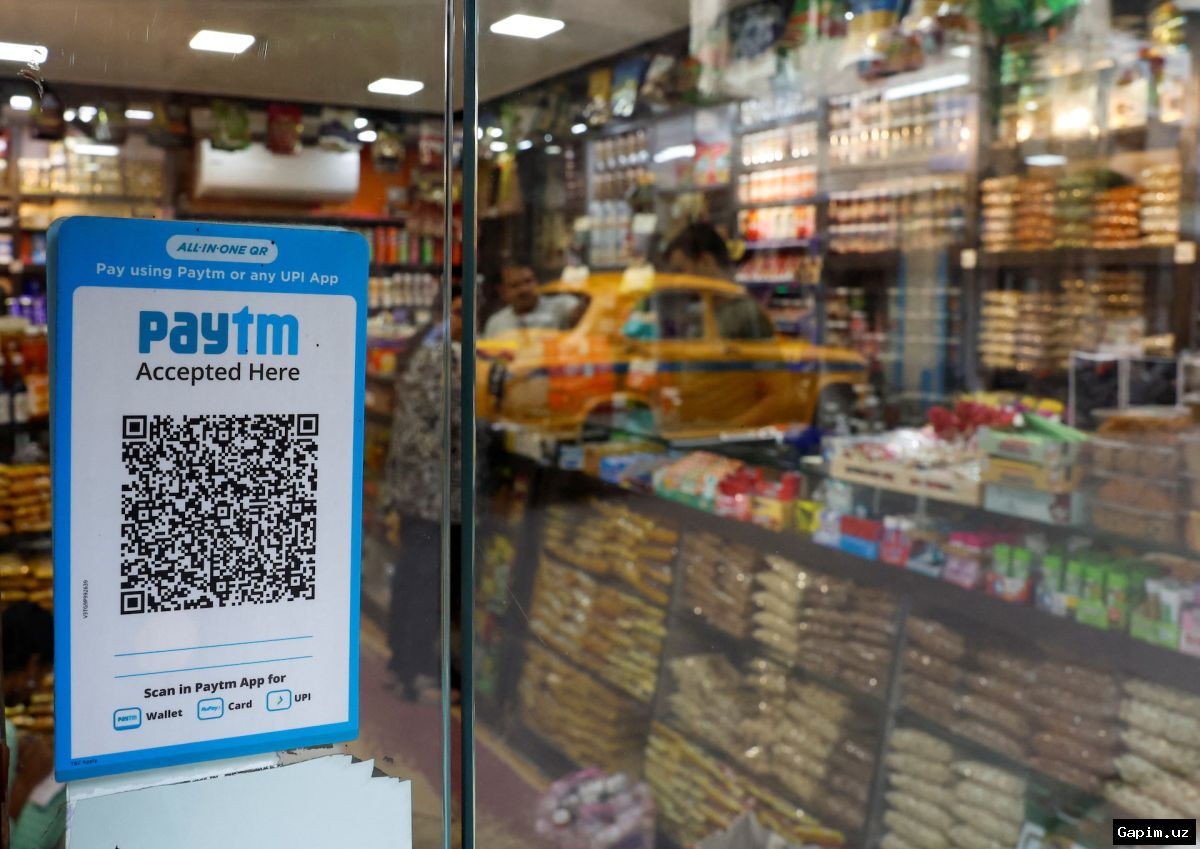
Since its introduction a decade ago, UPI has transformed how the world's largest population makes payments. From street vendors to global brands in shopping malls, QR codes are everywhere in India, as cash increasingly gives way to digital payments. Last month, UPI processed an all-time record of 24.51 billion transactions – that's 791 million transactions per day, worth more than $10bn daily. The government said it had processed 241.6 billion transactions in the last financial year, worth nearly $3.3 trillion, supporting 741 banks across the country. This transaction volume accounts for nearly half of all global real-time digital payment transactions daily.
Under the new policy, payments made to businesses worth more than 2,000 rupees ($20.84) will incur a levy of 0.4 percent, capped at 300 rupees ($3.13). All person-to-person transactions will remain free. Paying for other services, such as at fuel pumps, for railway tickets, or telecom bills, will have a flat fee of five rupees imposed per transaction. The government will bar merchants from passing on the additional cost to customers, but the reality is already shifting. Vikas Mahto, who operates an all-purpose grocery store in the National Capital Region, has already started charging a flat five-rupee ($0.05) fee on all transactions above 1,000 rupees ($10.42). "If the government charges us, we increase costs for customers," he told Al Jazeera. "It's simple maths."
The move has triggered a political storm in India, with the opposition accusing Modi of passing on costs to merchants under foreign pressure. "Here, the Modi government has given in to a US demand to get rid of zero MDR and charge for UPI. Why 0.4 percent MDR? Is this being done to enable US card companies to compete with UPI?" said Jairam Ramesh, a spokesperson for Congress. The US has previously criticised India's UPI framework, arguing that policies governing the system favour domestic payment providers and create an uneven playing field for US payment companies. While two US-owned payment apps – Google Pay and PhonePe – already process more than 80 percent of UPI transactions, the US Trade Representative's National Trade Estimate Report 2026 noted that US payment providers face unequal access to parts of the UPI ecosystem, particularly credit-card transactions on UPI.
Shares of Indian payment firms and banks rose on Wednesday, the day after the new policy was announced, as the change opens up new revenue streams for the firms which have so far absorbed costs for such transactions. Paytm, Axis Bank and Yes Bank gained between two and eight percent in early trade. The expansion of UPI has reshaped India's card economy with the near-collapse of debit card use. Since UPI offers instant bank-to-bank transfers with zero fees, debit cards have lost significant ground for everyday payments, with transaction volumes falling 67 percent between 2021 and 2025, according to the Reserve Bank of India. If that has hit the Indian debit card businesses of US-headquartered giants like Visa and Mastercard, the UPI system has also disadvantaged their credit cards. The homegrown RuPay is the only credit card that can be linked to the UPI — Mastercard and Visa cannot. Both companies have complained to the US Trade Representative about this practice, describing it as unfair.
Indian economist Santosh Mehrotra told Al Jazeera that there is no doubt that the current UPI system did not have a transparent or streamlined revenue model to sustain itself. In the face of influential banks and apps absorbing the costs, "the Modi government appears to be partially swayed by the US pressure as well here". "Banks and apps have multiplied profits through the ecosystem that UPI provided; therefore, it is unfair now to pass on costs to merchants to keep it alive," Mehrotra said. "In the end, customers will feel a further burden and the incentive to use UPI dies."
Source: www.aljazeera.com